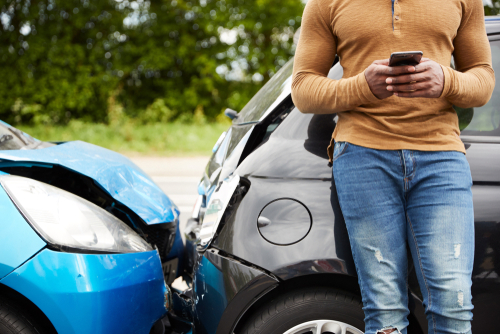
When the driver who hit you has no insurance, or not nearly enough, your recovery often depends on your own auto policy. Virginia generally requires auto liability policies issued or delivered in the state to include uninsured and underinsured motorist (UM/UIM) coverage, but collecting it isn’t automatic. Your own insurer evaluates the claim much like the at-fault driver’s insurer would.
At Deering Hedrick, P.C., our uninsured motorist lawyers help injured drivers, passengers, and pedestrians in Virginia Beach and across Hampton Roads identify every available policy and pursue the benefits available under applicable UM and UIM coverage. We handle the insurers so you can focus on your recovery. Contact Deering Hedrick, P.C. at (757) 383-6848 to discuss your car accident.
Virginia Uninsured Motorist Laws and Insurance Requirements
Under Virginia Code § 38.2-2206, every auto liability policy issued in Virginia must include UM coverage with limits at least equal to the state’s minimum liability requirements, which are currently $50,000 per person and $100,000 per accident for bodily injury and $25,000 for property damage. Your UM limits generally match your liability limits unless a named insured rejected the additional coverage in writing. The same endorsement must include UIM coverage with limits equal to your UM limits.
The statute defines “uninsured” broadly. A vehicle counts as uninsured if it has no liability insurance, if its insurer denies coverage for any reason, if its owner or driver is unknown, or if the owner or driver is legally immune from liability. Since July 1, 2024, Virginia no longer lets drivers pay a fee to register a vehicle without insurance, but uninsured drivers still cause crashes when policies lapse or coverage is denied.
Understanding Uninsured and Underinsured Motorist Accident Claims Process
A UM or UIM claim seeks benefits under an applicable auto insurance policy, which may be your own policy, the policy covering the vehicle you occupied, or a qualifying household policy. The insurer handling the claim may dispute fault, the extent of your injuries, and the value of your claim. Recovering benefits also requires establishing the other driver’s legal liability and the damages you are entitled to recover, while following applicable reporting and lawsuit-service requirements.
What Happens If You’re Hit by an Uninsured Driver?
Your UM coverage pays what you’re legally entitled to recover from the uninsured driver, up to your policy limits. Coverage isn’t limited to the policyholder. It can extend to a spouse and relatives living in the same household, anyone driving the insured vehicle with permission, and guests riding in it, so you may be covered even as a passenger or pedestrian. When more than one policy applies, Virginia law sets the order: the policy on the vehicle you occupied pays first, followed by policies where you’re a named insured, and then policies where you’re an insured but not the named insured.
If you file a lawsuit against the uninsured driver, Virginia requires you to serve a copy of the lawsuit on your UM insurer as though it were a party defendant. The insurer can then defend the case in the driver’s name or its own. In hit-and-run crashes, the case can proceed against the unknown driver as “John Doe.”
What Happens If the At-Fault Driver Doesn’t Have Enough Insurance?
When the at-fault driver’s policy isn’t enough to cover your losses, UIM coverage can make up the difference, up to your UIM limits. Under current Virginia law, UIM coverage is generally paid without a credit for the at-fault driver’s liability coverage, meaning it stacks on top of what that policy pays, unless a named insured on your policy signed an election to reduce UIM payments by the available liability coverage.
Virginia also allows you to settle with the at-fault driver’s liability insurer for its full available limits and then pursue your UIM claim. The statute sets specific requirements for that release so the UIM claim isn’t lost, which makes it important to have the paperwork reviewed before you sign.
How Virginia’s Contributory Negligence Rule Affects Your UM Claim
Virginia follows contributory negligence, one of the strictest fault rules in the country. If your own negligence was a proximate cause of the crash or your injuries, Virginia’s contributory negligence rule may bar recovery. Because UM coverage pays only what you’re legally entitled to recover from the other driver, this rule applies to UM and UIM claims as well, and insurers may raise contributory negligence to dispute your right to recover. Evidence such as witness statements, photographs, and crash footage can help address those allegations.
Unsure which policy may cover your injuries? Call Deering Hedrick, P.C. at (757) 383-6848 for a free consultation about your uninsured motorist claim
Compensation Available After an Uninsured Motorist Accident
UM and UIM coverage can pay for the same types of losses you could recover from an insured at-fault driver, including:
- Medical expenses: Emergency treatment, hospital stays, surgery, therapy, and future care.
- Lost income: Wages lost while recovering and reduced ability to earn in the future.
- Pain and suffering: Physical pain and emotional distress caused by the crash.
- Disability and disfigurement: Permanent limitations and scarring.
- Property damage: Compensation for vehicle repairs or replacement, subject to the applicable coverage limits.
- Wrongful death damages: Losses suffered by families when a crash is fatal.
Average Uninsured Motorist Accident Settlement Amounts
There is no single settlement amount that reliably predicts the value of a Virginia UM or UIM claim. Potential recovery depends on the injuries and losses, evidence of fault, and available insurance coverage. When multiple policies may apply, their limits and how they interact also affect the benefits available.
How Long Does It Take to Settle an Uninsured Motorist Claim?
The time needed to resolve a UM or UIM claim depends on your medical recovery, disputes over fault or coverage, the number of policies involved, and whether litigation is necessary. Before accepting a settlement, it is important to understand the likely effect of your injuries and any future treatment needs. Keep in mind that Virginia generally gives you two years from the date of the crash to file a personal injury lawsuit, and negotiations with your insurer don’t pause that deadline.
Have questions about the losses your coverage may address? Contact Deering Hedrick, P.C. at (757) 383-6848 to discuss your accident
What to Do After an Uninsured Motorist Accident
After a crash, these steps can help protect your health and preserve information for your claim:
- Call the police: Report the crash so there’s an official record, especially in hit-and-run cases.
- Get medical care: Seek treatment promptly, even if your injuries seem minor.
- Gather information: Get the other driver’s name, contact details, license number, and vehicle information, or note any details about a fleeing vehicle.
- Document the scene: Photograph the vehicles, the road, your injuries, and any visible damage, and collect witness contact information.
- Report the crash promptly to your insurer: If an unidentified driver caused the crash without making contact with your vehicle, or with you if you were a pedestrian, Virginia law specifically requires prompt reporting to your insurer or law enforcement.
- Get advice about statement requests: Before giving a recorded statement, consider speaking with an attorney about the request and any applicable policy obligations.
- Contact Deering Hedrick, P.C.: Call (757) 383-6848 so we can review your coverage and protect your claim from the start.
Is It Worth Suing an Uninsured Driver?
Whether pursuing the driver personally makes sense depends in part on whether the driver has income or assets available to satisfy a judgment. If a UM claim cannot be resolved through settlement, pursuing benefits may require a lawsuit against the uninsured driver and proper service on the UM insurer. A covered judgment may then be recoverable from the insurer, subject to the applicable coverage limits and legal requirements.
If the driver does have meaningful assets and your damages exceed your coverage, pursuing the driver directly may also make sense. Our guide on when to contact a lawyer after a car accident explains why getting advice early helps with these decisions.
Why Choose Deering Hedrick, P.C. for Your Uninsured Motorist Claim?
You need an attorney who will listen to what happened, explain your options, and take the work of pursuing your claim seriously. At Deering Hedrick, P.C., we pair accessibility with careful case preparation. Our founding attorneys bring more than 30 years of combined legal experience to clients throughout Virginia Beach, Chesapeake, Norfolk, and Hampton Roads.
We explain your coverage options, answer your questions, and keep you informed as your claim moves forward. Whether your case involves settlement discussions or litigation, you will understand our approach and what comes next.
Contact Deering Hedrick, P.C. at (757) 383-6848 for a free consultation about your uninsured motorist claim.